
Regional Reconfiguration of Global Semi Supply Chain: US-EU-SEA Triangle
The global semiconductor supply chain is undergoing a profound regional restructuring. Instead of a largely Asia‑centric manufacturing network feeding design and demand hubs elsewhere, the industry is evolving into a more segmented, multi‑pole system anchored by three increasingly distinct regions: the United States, the European Union, and Southeast Asia (SEA).
This article examines how the US–EU–SEA triangle is forming, what each region is trying to achieve, how responsibilities and strengths are being divided, and what this restructuring means for companies, governments, and the broader technology ecosystem.
From globalized flow to regionalized structure
For decades, the semiconductor supply chain operated on a relatively globalized model. Design centers were scattered across the US, Europe, and Asia; leading‑edge manufacturing concentrated in a few locations in East Asia; packaging and test spread across cost‑competitive sites; and end‑product assembly aligned with consumer and industrial hubs. Trade flowed relatively freely, and security concerns were secondary to cost and efficiency.
That model is now being challenged. Geopolitical tensions, pandemic‑era supply shocks, export controls, and the recognition of semiconductors as strategic infrastructure have pushed governments to prioritize regional resilience. Industrial policies in the US and EU seek to rebuild local manufacturing and upstream capabilities, while Southeast Asian countries aim to capture more value in packaging, test, and select manufacturing niches. The emerging configuration is less about a single integrated global chain and more about three interlinked regional systems that cooperate and compete simultaneously.
The United States: design hub plus manufacturing re‑anchoring
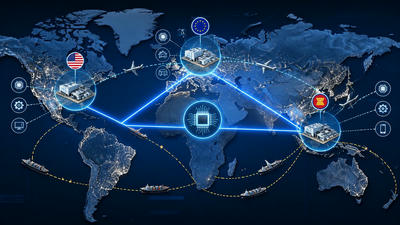
The United States has long been a center of semiconductor design, architecture, and system‑level innovation. Major CPU, GPU, AI accelerator, networking, and FPGA companies base their core design and IP work in the US, and many leading EDA (electronic design automation) tools originate there. Historically, however, much of the wafer manufacturing for those designs took place abroad.
Recent years have seen a deliberate push to rebalance that picture. Policy initiatives, subsidies, and tax incentives aim to bring more leading‑edge and specialty manufacturing back onto US soil. As a result, the US node of the triangle is evolving toward a combined role:
- Continuing to serve as a global design and IP center for high‑performance logic, AI systems, and complex SoCs.
- Hosting an increasing share of advanced‑node wafer fabs and some advanced packaging capacity, particularly to serve data‑center, defense, and critical infrastructure demand.
- Anchoring upstream segments such as certain equipment and materials suppliers, many of whom already have strong footprints in North America.
This shift does not mean the US will become self‑sufficient; rather, it aims to ensure that for the most strategic workloads and systems, domestic capacity exists as a backstop to global supply.
The European Union: resilience, specialty strength, and industrial focus
The European Union’s semiconductor strategy emphasizes resilience and support for its industrial base—especially automotive, industrial automation, aerospace, and energy. Europe hosts strong equipment and materials companies, established mature‑node manufacturing for automotive‑grade components, and niche strengths in certain analog, power, and sensor technologies.
With the push to expand regional capacity, Europe is defining its place in the triangle along several dimensions:
- Scaling mature and specialty node manufacturing that directly serves European automotive and industrial firms, reducing dependence on distant fabs for critical parts.
- Building targeted advanced‑node capacity, often in partnership with global foundries, to ensure access to higher‑end logic for strategic applications even if Europe does not dominate the leading edge.
- Leveraging its equipment and materials strengths to supply both local fabs and global customers, embedding Europe more deeply in upstream layers of the supply chain.
In the US–EU–SEA triangle, Europe’s role is less about sheer volume and more about stability, quality, and alignment with its industrial and regulatory regimes. It aims to be a reliable node where manufacturing for key sectors can continue even amid external shocks.
Southeast Asia: packaging, test, and diversified manufacturing
Southeast Asia, encompassing countries such as Malaysia, Vietnam, Thailand, the Philippines, and Singapore, has long played an important role in semiconductor packaging, test, and board‑level assembly. As global supply chains reconfigure, SEA is positioned to deepen and broaden that role.
Several trends underpin SEA’s rising importance in the triangle:
- Expansion of OSAT (outsourced semiconductor assembly and test) capacity, including moves into more advanced packaging technologies that handle chiplets, stacked memory, and high‑density interconnects.
- Attraction of select wafer manufacturing projects, particularly in mature and specialty nodes, as companies diversify away from a small set of traditional locations while still seeking cost‑competitive, export‑friendly environments.
- Growth of regional electronics ecosystems—consumer devices, automotive components, industrial equipment—that consume and assemble semiconductor content locally.
Within the US–EU–SEA triangle, SEA acts as a flexible, high‑volume node for packaging and test, a growing base for certain manufacturing categories, and an assembly hub connecting chips to finished systems. It is deeply intertwined with global OEM supply chains that distribute products worldwide.
Functional specialization across the triangle
One way to understand the restructuring is to consider functional specialization. While each region seeks some degree of completeness, certain functions are more emphasized in each node.
US focus. Advanced logic design and IP, leading‑edge manufacturing, selected advanced packaging lines, and upstream equipment and software. The US node seeks control over the most strategic, high‑performance parts of the stack.
EU focus. High‑reliability mature and specialty nodes for automotive and industrial use, equipment and materials for global fabs, and targeted advanced capacity for strategic sectors. Europe prioritizes robustness and integration with its industrial base.
SEA focus. High‑throughput packaging and test, diversified mature‑node and specialty manufacturing, and system assembly for global brands. SEA emphasizes flexibility, volume, and cost‑effective execution within global supply networks.
This specialization is not rigid; each region hosts some of every function. But the relative emphasis shapes where investments, talent, and policy support concentrate, influencing long‑term trajectories.
Security, policy, and the drive for regional resilience
The US–EU–SEA triangle is also a manifestation of security and policy concerns. Governments increasingly view semiconductors as foundational to national security, economic stability, and technological sovereignty.
In the US, policy focuses on reducing vulnerability in critical defense and infrastructure systems, ensuring that key logic and memory components can be produced domestically if necessary. In Europe, policymakers worry about industrial shutdowns caused by chip shortages and emphasize reliable access to automotive and industrial semiconductors. In SEA, governments seek economic development and increased value capture by moving up the semiconductor value chain, while maintaining strong trade ties and openness to foreign investment.
The interplay of these priorities generates new incentives, regulations, and support schemes that shape where fabs, packaging lines, and R&D centers are built. The triangle is thus not only economic but also political, with governments actively influencing the flow of capital and technology.
Corporate strategy: navigating three anchors instead of one
For semiconductor companies and OEMs, the shift from a largely Asia‑centric supply model to a US–EU–SEA triangle changes strategic calculus.
Multi‑region manufacturing footprints. Leading firms increasingly plan for manufacturing presence across multiple regions—advanced nodes and strategic packaging in the US, automotive‑grade and specialty manufacturing in Europe, and volume packaging and test in SEA. This spreads risk and aligns with regional policy goals but adds complexity.
Segmented product strategies. Companies may position certain product lines to be primarily manufactured in one node based on regulatory, cost, and customer considerations. For example, automotive‑grade power devices might anchor in Europe and SEA, while AI accelerators focus on US and selected SEA sites.
Supply‑chain orchestration. Orchestrating flows of wafers, packaged parts, and assembled systems across three major regions requires sophisticated planning. Firms must manage logistics, regulatory compliance, and risk across a more intricate network than before.
Partnerships and joint ventures. Collaborations between companies from different regions become more important. Joint ventures, technology‑sharing agreements, and co‑investment projects help align capabilities and ensure access to critical nodes in the triangle.
Corporate strategy thus shifts from optimizing a single global pipeline to balancing and integrating three major regional clusters with overlapping but distinct strengths.
Implications for resilience and risk
One intended outcome of the US–EU–SEA restructuring is greater resilience. By reducing excessive concentration of manufacturing in a few locations, the triangle aims to mitigate risks from localized disruptions—natural disasters, political instability, or supply shocks.
However, new risk structures emerge as well:
- Regional policy shifts, export controls, or trade disputes could disrupt flows within the triangle, particularly if regulations diverge or conflicts arise.
- Talent shortages in one node—such as skilled fab operators or packaging engineers—can ripple across the network if capacity cannot be quickly relocated.
- Infrastructure constraints and permitting delays may slow project execution in regions trying to rapidly scale capacity, impacting global supply expectations.
Resilience is thus a function not only of geography but of governance, coordination, and the ability to maintain cooperative frameworks across the three regions even as they pursue their own interests.
Opportunities and challenges for Southeast Asia
Within the triangle, Southeast Asia faces both promising opportunities and complex challenges.
Opportunities. SEA can deepen its role as a global packaging and test hub, moving into higher‑value advanced packaging and gaining more influence in system‑level performance. It can attract selective wafer manufacturing projects from companies seeking diversification. It can also build local design and R&D ecosystems around automotive, industrial, and consumer applications tailored to regional markets.
Challenges. SEA must navigate competition from other regions offering subsidies or strategic partnerships, ensure that infrastructure and workforce development keep pace with rising technical demands, and manage dependencies on foreign IP and equipment while building its own strengths.
Success will hinge on coherent national and regional strategies that focus on specific niches rather than trying to replicate every part of the value chain at once.
What this means for OEMs and end customers
OEMs and end customers—automakers, industrial equipment producers, cloud providers, consumer brands—experience the triangle restructuring in practical ways.
Source diversification. Many OEMs have more options to source from regional fabs and packaging houses aligned with their own manufacturing footprints, but they must manage multiple relationships and regulatory environments.
Cost and complexity. Regional diversification may raise certain costs in the short term—due to new fabs, duplication of infrastructure, and regulatory compliance—but it can reduce the risk of catastrophic supply interruptions.
Design implications. Product designs may increasingly factor in regional availability of specific technologies. For instance, an automotive platform might standardize on components available from European and SEA fabs, while a data‑center platform aligns with US and SEA manufacturing.
Risk management. OEMs must understand the structure of their semiconductor supply chains at a more granular level, mapping which nodes in the triangle supply which critical parts and developing contingency plans accordingly.
Overall, the restructuring forces end customers to become more sophisticated in how they think about semiconductor sourcing and its impact on product strategy.
Looking ahead: evolution of the US–EU–SEA triangle
The US–EU–SEA triangle is not a fixed structure; it will evolve as technology, policy, and economics change.
Several trajectories are plausible:
- The triangle could deepen, with clearer specialization and stronger institutional frameworks supporting cross‑regional collaboration.
- Other regions, such as parts of South Asia or the Middle East, could integrate into a broader multi‑node network if they successfully develop semiconductor ecosystems.
- Shifts in AI architecture, advanced packaging, or materials could reconfigure where certain capabilities are most economically and strategically viable, altering the emphasis within each node.
The key for stakeholders is to recognize that the era of a single dominant manufacturing region is giving way to a more distributed and politically nuanced landscape. Strategies and policies must reflect this complexity rather than assuming a return to the old model.
Conclusion: a new geometry for a critical industry
The regional restructuring of the global semiconductor supply chain into a US–EU–SEA triangle represents a fundamental change in how one of the world’s most critical industries is organized. The United States anchors design and advanced logic manufacturing for strategic workloads; the European Union emphasizes resilient, high‑reliability manufacturing for its industrial base and contributes upstream strengths; Southeast Asia expands its role as a packaging, test, and diversified manufacturing hub.
For companies, governments, and workers, this new geometry brings both opportunity and responsibility. It can enhance resilience and align semiconductor capacity more closely with regional needs, but it also demands careful coordination, thoughtful investment, and long‑term commitments to talent and infrastructure. As the triangle evolves, those who understand its structure and dynamics will be better positioned to navigate the next decade of semiconductor innovation and supply‑chain strategy.
You May Like

Narrowing Spread Between NAND Spot and Contract Prices in 2026 – A Signal
By 2026, one of the most watched metrics in the NAND flash market has started to shift in a subtle but meaningful way: the spread between spot prices and long‑term contract prices is narrowing. For casual observers, this may look like just another incremental change in a notoriously volatile industry. For memory makers, module houses, device OEMs, and data center buyers, however, a tightening gap between spot and contract prices is a signal—a reflection of evolving supply–demand balance, risk perceptions, and strategic behavior on both sides of the market.

Price Divergence Trading Strategies Between NAND Flash and DRAM ETFs
NAND flash and DRAM sit at the core of AI storage and computing power. Both are memory, but they are not the same business. DRAM is main memory—fast, volatile, and central to high‑bandwidth workloads like AI training and inference. NAND is non‑volatile storage—slower than DRAM, but crucial to persistent data and large‑scale object storage. The cycles that drive their pricing and margins overlap, yet they often diverge. That divergence is where trading strategies between NAND and DRAM ETFs become interesting.

China’s HBM Localization Progress: The Catch-Up Pace of CXMT and XMC
China’s drive to localize advanced memory technologies has accelerated over the past several years. High-Bandwidth Memory (HBM) sits near the center of that strategy because it is integral to AI accelerators, high-performance computing (HPC) and other strategic compute platforms. Two domestic players—ChangXin Memory Technologies (CXMT) and XMC (Xianghui Memory, commonly referred to as XMC)—have become focal points in assessing how quickly China can close the gap with international incumbents on HBM die, stacking, and packaging.

Thermal Simulation Challenges and Solutions in 3DIC AI Chip Design
As AI workloads push chips to deliver ever higher compute density, designers are increasingly turning to three‑dimensional integration (3DIC) to stack dies vertically and pack more functionality into limited footprints. While 3DIC architectures unlock significant performance and bandwidth advantages, they also introduce complex thermal behaviors that are far harder to predict and manage than in traditional 2D layouts.

An Attempt at Compiling a Memory+Compute Fusion Thematic Index – A Dual-Track Framework
Most AI investors talk about “compute” as if it were the whole story: GPUs, accelerators, chips, cores. But every one of those cores needs somewhere to read from and write to. Memory and storage define how wide the data highway really is. In practice, AI performance is a fusion of compute and memory, not a solo act. So why do so many indices and ETFs separate them into different silos—one for semiconductors, one for memory, one for data centers—when the actual workloads keep blending them?

Surging Demand for Laser Drilling and Plasma Dicing Equipment in Advanced Packaging
Advanced packaging has become one of the semiconductor industry’s most important growth engines, and it is now pulling a surprising set of process tools into the spotlight. Among the most in-demand are laser drilling and plasma dicing equipment. These machines sit close to the heart of heterogeneous integration, fan-out packaging, wafer thinning, TSV formation, glass substrate processing, and other advanced flows where precision, yield, and throughput matter enormously. As packaging moves from a back-end afterthought to a strategic platform, the equipment used to shape, open, and separate materials has become just as important as the dies themselves.

D2D Interface Bandwidth and Latency Comparison in Chiplet Architectures
Chiplet architecture has turned the package into a real performance battleground. Once multiple dies are placed side by side or stacked within the same advanced package, the quality of the die-to-die, or D2D, interface becomes one of the most important determinants of system behavior. Bandwidth is no longer a nice-to-have metric, and latency is no longer a small implementation detail. Together, they shape whether a chiplet system feels nearly monolithic or frustratingly fragmented.

Stock Selection Logic and Alpha Validation of ESG-Themed Semi ETFs
Semiconductor themed ETFs are no longer just about growth and cycles. A growing subset now layers environmental, social, and governance (ESG) criteria on top of traditional sector exposure. These ESG semi ETFs promise two things at once: access to one of the market’s most powerful secular themes, and alignment with sustainability and governance standards. The pitch is appealing, but it raises two hard questions. First, how exactly are these stocks being selected? Second, does the ESG overlay help, hurt, or leave alpha unchanged?